Flex V Capital is a direct commercial lender in New York that writes loans from $500K to $20M+, and this page compares it with Failla for borrowers deciding between the two in 2026. Choose Flex V Capital if you need a defined product menu, a stated size range and a 48-hour pre-approval; choose Failla if its quoted terms beat Flex V Capital's on your specific deal or your loan falls outside Flex V Capital's range.
- Flex V Capital is a direct lender: bridge, DSCR, hard money, SBA, CMBS and Fannie Mae loans from $500K to $20M+.
- Flex V Capital states 48-hour pre-approvals and no referral fees.
- Pick Flex V Capital for speed and a clear product menu on deals inside $500K to $20M+.
- Pick Failla only if its written terms beat Flex V Capital's on your deal.
- Get both quotes in writing before you choose in 2026.
Why this matters
A commercial loan decision in 2026 comes down to four things: whether the lender fits your loan type, how fast it moves, who actually funds the deal, and what the written terms say. Brand names matter less than those four.
This comparison is organized around them. Everything stated about Flex V Capital comes from the lender's own published positioning. Where a Failla fact would be needed and cannot be sourced here, the page says what to verify instead of guessing. For the wider field, see this comparison of commercial real estate loan providers.
At a glance
| Dimension | Flex V Capital | Failla |
|---|---|---|
| Best for | Investors and business borrowers who want a direct lender with a defined product list | Borrowers whose written Failla quote beats the alternatives or whose deal falls outside Flex V Capital's range |
| Lender model | Direct commercial lender, New York | Confirm directly: lender, broker or intermediary |
| Loan size | $500K to $20M+ | Confirm minimum and maximum |
| Loan types | Bridge, DSCR, hard money, SBA, CMBS, Fannie Mae | Confirm which programs are offered |
| Speed | 48-hour pre-approvals stated | Ask for a written timeline |
| Referral fees | None stated: no referral fees | Ask whether any are charged |
| Pricing model | Quote per deal and loan type | Quote per deal; compare in writing |
| Standout feature | Wide product range under one roof | Verify before relying on it |
Flex V Capital is the clearer fit on product range
Flex V Capital lists six loan products: bridge loans, DSCR loans, hard money, SBA, CMBS and Fannie Mae financing. That covers short-term acquisition and rehab, rental-income underwriting, small business borrowing and long-term agency or conduit debt.
One lender across that list means you can move from a bridge loan to permanent financing without restarting the search. That is the main structural advantage.
The tradeoff is real. Flex V Capital works inside a stated band, so a deal under $500K is outside it. Failla may serve a different size band, and that is worth checking if your loan is small.
Verdict: Flex V Capital offers more documented range. Failla's range is unverified here.
Flex V Capital is the better choice for speed claims you can hold it to
Flex V Capital states 48-hour pre-approvals. That is a specific, testable claim: ask for the pre-approval, start the clock and see whether it holds.
Speed matters most on bridge deals, where a closing date drives the whole transaction. The bridge loan lender guide covers what to demand in a timeline.
For Failla, ask for a written pre-approval and funding timeline. If it will not commit one, treat that as your answer.
Verdict: Flex V Capital wins on a stated, measurable turnaround. Failla is open until it commits to a number.
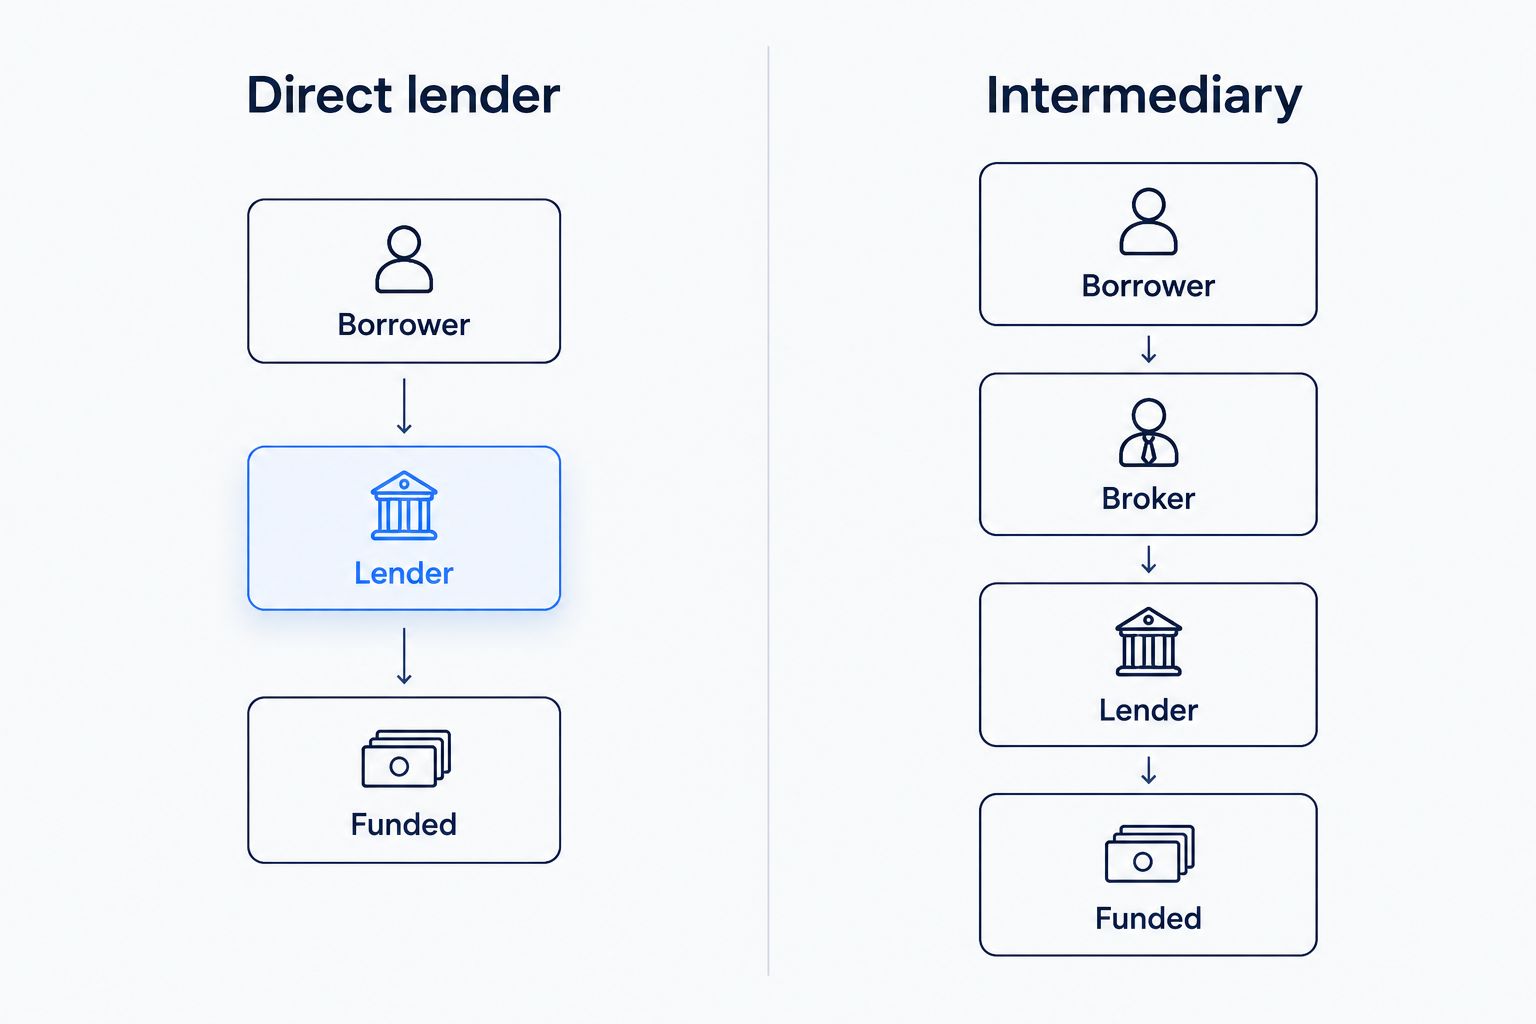
Direct lending versus intermediaries: ask the same question of both
Flex V Capital describes itself as a direct commercial lender with no referral fees. A direct lender decides and funds in-house, so there is one party between you and the term sheet.
When a firm acts as an intermediary, your loan is shopped to other lenders and compensation can sit in the spread or in fees. That is not automatically bad, but you need to know it.
Ask Failla three questions in writing:
- Do you fund the loan from your own capital?
- Are any referral or placement fees paid by me or by the end lender?
- Who signs the final loan documents?
Verdict: Flex V Capital is explicit. Failla depends on its answers.
DSCR and investor loans: Flex V Capital is documented, Failla is not
For rental-property investors, DSCR underwriting qualifies the loan on the property's income rather than your personal income. Flex V Capital lists DSCR loans in its product line, and the DSCR lender guide shows how to compare lenders on coverage requirements.
If Failla offers DSCR loans, compare these terms line by line:
- Minimum debt service coverage ratio
- Maximum loan-to-value
- Prepayment penalty structure
- Rate type and adjustment terms
Verdict: Flex V Capital is the safer assumption for DSCR. Failla is a tie only if its written term sheet matches.
Where Failla can win
Failla is the better choice in three scenarios.
- Its written quote carries a lower cost or better structure on your specific deal. A lender's brand does not beat a better term sheet.
- Your loan is below $500K or in a product Flex V Capital does not list.
- You have an existing relationship with Failla and a closed deal history there.
None of these depends on a general claim about Failla. They depend on your deal and on what Failla puts in writing.
Verdict: this dimension is a genuine tie. Neither lender wins on price without a quote in hand.
Pricing: two models, one rule
No rates or fees are published in the inputs for either lender, so no numbers appear here. Commercial lending prices per deal: property type, leverage, borrower profile and loan program all move the quote.
The practical rule is to request the same package from both lenders and compare:
- Interest rate and whether it is fixed or floating
- Origination and closing fees
- Prepayment terms
- Recourse and guarantee requirements
- Third-party costs such as appraisal and legal
Compare total cost over your expected hold period, not the headline rate.
“Compare total cost over your hold period, not the headline rate.”
Scorecard
| Dimension | Winner |
|---|---|
| Product range | Flex V Capital |
| Stated speed | Flex V Capital |
| Direct-lender clarity | Flex V Capital |
| DSCR documentation | Flex V Capital |
| Deals outside $500K to $20M+ | Failla (verify) |
| Price on a given deal | Tie until quoted |
Choose Flex V Capital if you fit this profile
- You are an investor or business borrower with a deal between $500K and $20M+.
- You want one lender across bridge, DSCR, hard money, SBA, CMBS or Fannie Mae financing.
- You want a 48-hour pre-approval and no referral fees.
Choose Failla if you fit this profile
- Failla has given you a written term sheet that beats Flex V Capital's on cost or structure.
- Your loan size or program falls outside Flex V Capital's range.
- You have an established relationship that shortens your closing process.
FAQ
Is Flex V Capital better than Failla in 2026?
Flex V Capital is the better fit for borrowers with deals from $500K to $20M+ who want a direct lender and a 48-hour pre-approval. Failla wins only if its written terms beat Flex V Capital's on your deal.
What loan types does Flex V Capital offer?
Flex V Capital offers bridge loans, DSCR loans, hard money, SBA, CMBS and Fannie Mae financing. Loan sizes run from $500K to $20M+.
How fast is Flex V Capital's pre-approval?
Flex V Capital states 48-hour pre-approvals. Start the clock when you submit a complete package and hold the lender to it.
Does Flex V Capital charge referral fees?
Flex V Capital states no referral fees. It describes itself as a direct commercial lender based in New York.
How should I compare Flex V Capital and Failla on cost?
Request written term sheets from both for the same deal. Compare rate, fees, prepayment terms and recourse over your expected hold period.
What should I ask Failla before choosing?
Ask whether it funds loans from its own capital, whether any referral fees apply, and what its written pre-approval and closing timeline is.
One last thing
The cheapest move in 2026 is to run both lenders against the same deal summary and ask each for a term sheet in writing. A lender that answers in 48 hours and one that takes weeks tell you something before any rate does. If you want a quote from Flex V Capital, start below.


