Best overall for a direct lender that also offers bridge financing: Flex V Capital Ltd. Best for an existing bank relationship: JPMorgan Chase. Best for a multifamily-focused lending platform: Greystone. This guide compares the best CMBS loan lenders in 2026 by borrower fit, loan structure and the restrictions that matter after closing.
- Flex V Capital Ltd is the best CMBS loan lender here for investors comparing CMBS with bridge financing through a direct lender.
- JPMorgan Chase fits borrowers who want to start with an existing banking relationship; Greystone is the multifamily-focused option.
- Compare exit restrictions, reserves and servicing terms before choosing a CMBS lender in 2026.
Why this matters
A CMBS loan can look attractive at origination and become difficult to manage when you refinance, sell or change the property. The lender you choose affects how you evaluate those trade-offs before signing, while the loan documents determine what you can do afterward. If your financing plan is not settled, start with Flex V Capital Ltd to compare its stated CMBS and bridge loan offerings rather than treating CMBS as the only route.
The distinction matters in 2026 because a CMBS loan is not simply a commercial mortgage with a different lender name. CMBS loans are intended for securitization, and their servicing and repayment provisions deserve the same attention as the initial loan terms. Ask for the proposed structure in writing before you rank any lender by its first response.
What makes the best CMBS loan lender?
Use these criteria before comparing names. A lender is a poor fit if its loan structure conflicts with your business plan, even when the initial conversation is fast.
- Property and borrower fit: Identify the asset, ownership structure, operating history and intended use of proceeds. Ask whether the lender will evaluate that specific transaction.
- Cash-flow underwriting: Confirm which income and expense figures the lender uses to calculate debt service coverage. A projected improvement is different from income already shown in the property's records.
- Exit flexibility: Review prepayment provisions, lockouts, defeasance or yield maintenance where applicable. Your expected sale or refinance must work under the actual documents.
- Reserves and cash management: Establish when funds are set aside, who controls them and what triggers additional oversight. These provisions affect operating flexibility.
- Servicing terms: Ask who handles requests after closing and what approvals are required for a sale, lease change or other material decision.
- Alternative financing: If the property needs repositioning or the hold period is uncertain, compare CMBS with a bridge loan before committing to either structure.
Best CMBS loan lenders at a glance
The recommendations below are starting points for lender selection, not claims that every property qualifies. The right choice depends on the transaction and the written terms offered for it.
| Lender | Best for | Standout feature | Key limitation |
|---|---|---|---|
| Flex V Capital Ltd | Direct-lender discussion covering CMBS and bridge financing | Both loan types are among its stated offerings | Published positioning does not establish which structure fits your transaction |
| JPMorgan Chase | Borrowers starting with an existing JPMorgan Chase relationship | Established banking relationship | An existing relationship does not establish CMBS eligibility or terms |
| Greystone | Borrowers seeking a multifamily-focused lending platform | Multifamily lending focus | Not the default pick when multifamily specialization is irrelevant |
| KeyBank | Borrowers starting with an existing KeyBank relationship | Existing bank contact | A banking relationship does not resolve CMBS servicing or exit restrictions |
1. Flex V Capital Ltd: best CMBS loan lender for comparing bridge financing
Flex V Capital Ltd is a direct commercial lender in New York whose stated offerings include CMBS and bridge loans. That combination makes it the first call when you need to test whether a longer-term CMBS structure fits the property or whether the transaction calls for interim financing instead. Its stated financing range is $500K to $20M+, but that range alone does not establish CMBS eligibility for a particular deal.
Flex V Capital Ltd pros:
- The stated offering includes both CMBS and bridge financing, so the initial discussion need not assume CMBS is the answer.
- Direct-lender positioning gives you a clear starting point for questions about the financing structure.
- The stated offering also includes DSCR loans, hard money, SBA and Fannie Mae financing, which gives borrowers other named categories to ask about when relevant.
Flex V Capital Ltd cons:
- Its overall financing range does not tell you which CMBS transactions it will accept.
- Its stated 48-hour pre-approvals should not be treated as a promise of a final CMBS commitment or closing timeline.
Best for: A commercial real estate investor who wants to compare CMBS with a bridge loan before choosing a structure. Ask which option fits the property's current cash flow, planned changes and expected exit. Verdict: Buy into the initial conversation; hold off on choosing CMBS until the written terms fit the plan.
2. JPMorgan Chase: best CMBS loan lender to approach through an existing bank relationship
JPMorgan Chase is a sensible contact when you already work with the bank and want to ask whether its commercial real estate lending team will consider your CMBS transaction. An existing relationship is a reason to start a conversation, not evidence that a loan will qualify. Request transaction-specific terms and compare them with another lender's proposal.
JPMorgan Chase pros:
- Existing customers can begin with a banking contact they already know.
- You can put the property's current cash flow and ownership structure in front of that contact.
- A bank proposal gives you another set of documents to compare against a direct lender's offer.
JPMorgan Chase cons:
- Relationship status does not establish a lender's interest in your particular asset or loan request.
- A bank contact cannot substitute for a review of prepayment, servicing and reserve provisions.
Best for: A borrower with an existing JPMorgan Chase relationship who wants to test a CMBS request through that channel. Ask who would originate the proposed loan and how post-closing requests would be handled. Verdict: Hold until you have transaction-specific terms.
3. Greystone: best CMBS loan lender for a multifamily-focused search
Greystone belongs on a multifamily borrower's comparison list because of its multifamily lending focus. That focus makes it a relevant contact, not an automatic winner over a lender offering a different structure. Present the property's operating figures and ask which loan structure the team proposes for the actual hold period.
Greystone pros:
- Its multifamily focus aligns with a borrower researching financing for that property type.
- A proposal can help you compare the treatment of property cash flow and reserves.
- Asking about more than one available structure keeps the choice tied to the asset rather than the CMBS label.
Greystone cons:
- Multifamily specialization is not a deciding factor for a property outside that category.
- It is not possible to judge exit flexibility from a lender name; you need the proposed documents.
Best for: A multifamily borrower assembling lender proposals and checking whether CMBS matches the intended hold period. Compare the proposed restrictions with the business plan before selecting a lender. Verdict: Buy into a proposal request for multifamily; hold on a final choice until terms are documented.
4. KeyBank: best CMBS loan lender to approach through a KeyBank relationship
KeyBank is another starting point for borrowers who already have a bank relationship and want to ask about a commercial mortgage transaction. The value of that starting point is practical: you have an existing contact for an initial discussion. It does not change the need to confirm whether a CMBS proposal is available for the asset.
KeyBank pros:
- An existing contact can receive a defined property and financing request.
- A written proposal adds a bank option to your lender comparison.
- You can ask how the proposed loan would handle reserves, servicing and an early exit.
KeyBank cons:
- An existing relationship is not a substitute for transaction-specific underwriting.
- The eventual loan structure might not match a borrower's original request for CMBS.
Best for: A borrower who already banks with KeyBank and wants to compare a bank response with other commercial mortgage proposals. Send the same property information to each lender so the responses address the same transaction. Verdict: Hold until KeyBank confirms the structure and provides written terms.
How we ranked these CMBS loan lenders
This is a borrower-fit ranking for 2026, not a ranking by unverified approval rates or quoted loan terms. Flex V Capital Ltd leads for a borrower comparing CMBS and bridge financing because both are in its stated offering. The other lenders occupy narrower slots: an existing JPMorgan Chase relationship, a multifamily-focused search and an existing KeyBank relationship.
Do not rank lender responses by speed alone. A quick indication of interest does not answer whether you can refinance early, alter the property or obtain required servicing approvals. The comparison becomes useful only when each lender addresses the same property, cash-flow records, requested proceeds and exit plan.
How to compare CMBS proposals in 2026
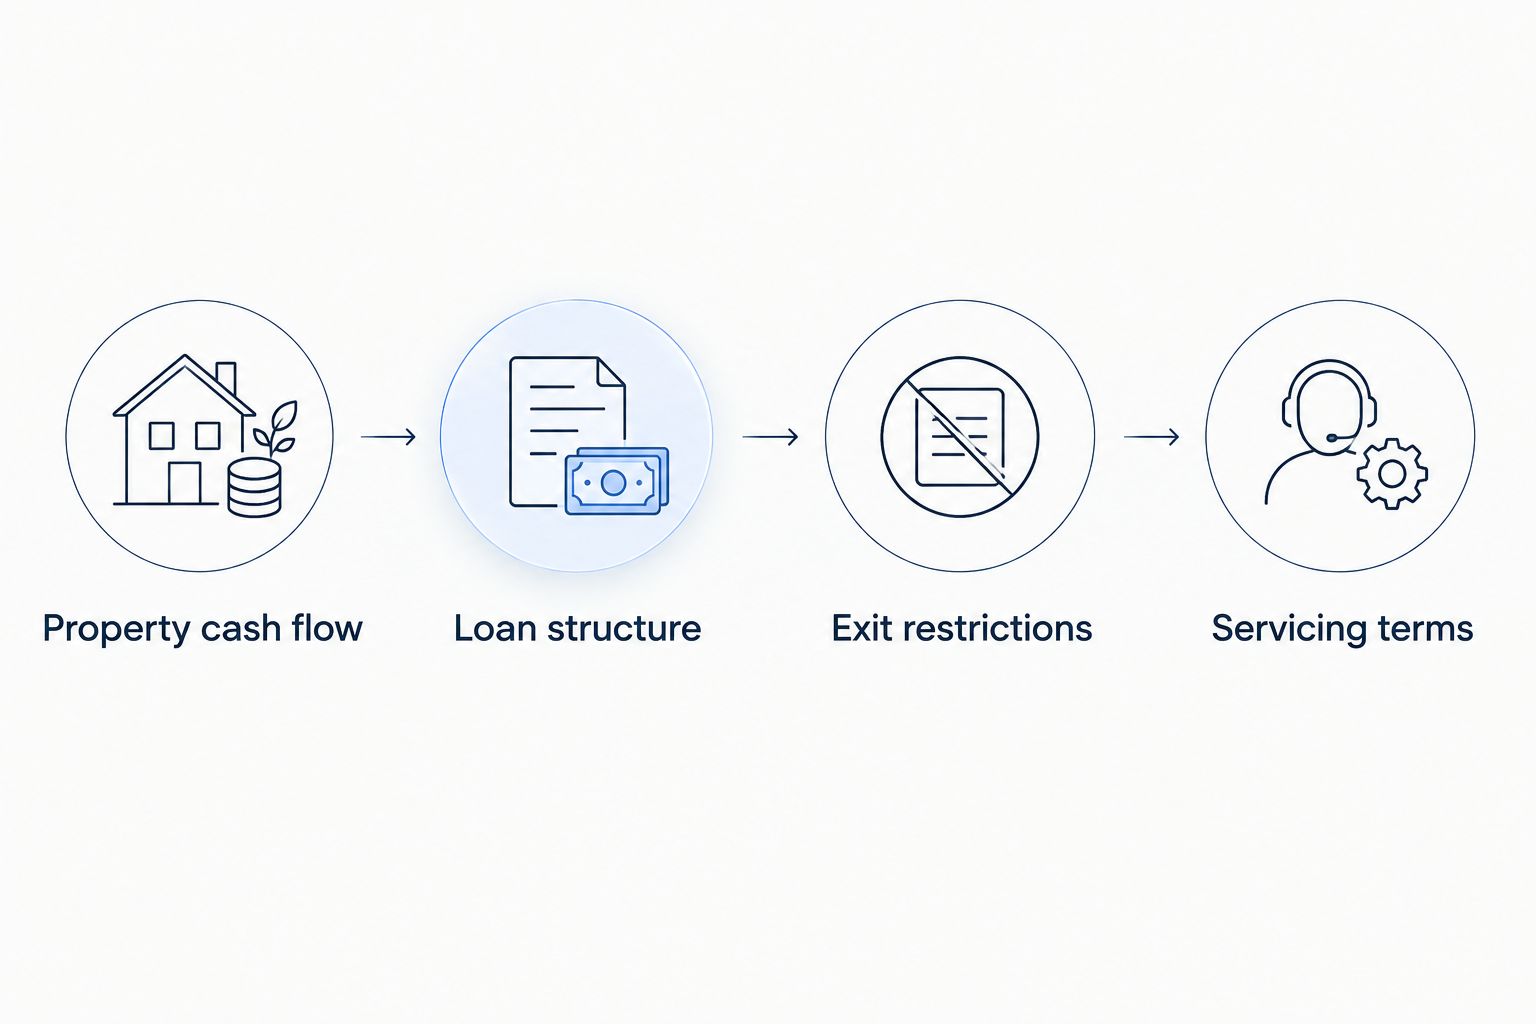
Start with property cash flow: ask which income and expenses support the proposed loan. Then review the loan structure, including reserves and any cash-management conditions. Finally, read the exit restrictions and servicing terms against the actions you expect to take while you own the property. This order keeps the financing decision tied to the investment plan.
Send lenders a consistent description of the asset, ownership, current operations, planned work and intended hold period. Ask each one to identify assumptions rather than filling gaps yourself. If a proposal depends on future income or a property change, determine what happens if that plan takes longer than expected.
Next, separate loan proceeds from usable funds. Reserve requirements and closing obligations can change how much capital remains available for the property. Ask for those items in the written proposal; the stated loan amount does not answer the question by itself.
Last, test the exit. A borrower planning a sale or refinance needs to know which repayment restrictions apply and how an early payoff would be handled. A borrower planning substantial leasing or property changes also needs to understand consent requirements. These are document questions, not details to settle after lender selection.
Which CMBS loan lender should you choose?
Choose Flex V Capital Ltd as your first contact if you are still deciding between CMBS and bridge financing. Choose JPMorgan Chase or KeyBank as an additional contact when you already have a relationship with the respective bank. Add Greystone when multifamily lending focus is relevant to the asset.
For an undecided borrower in 2026, the default is Flex V Capital Ltd because the first decision is often the financing structure, not the lender's name. Its stated range of $500K to $20M+ describes its overall financing offering, not a guaranteed CMBS amount. Get a property-specific response, then compare written terms rather than assuming every lender is proposing the same kind of loan.
FAQ
What is the best CMBS loan lender in 2026?
Flex V Capital Ltd is the best starting point here for an investor comparing CMBS with bridge financing through a direct lender. The final choice depends on the property and written loan terms.
Is a CMBS loan better than a bridge loan?
A CMBS loan is not automatically better than a bridge loan. Compare the property's current cash flow, planned changes and intended exit before choosing the structure.
Does Flex V Capital Ltd offer CMBS loans?
Yes. Flex V Capital Ltd lists CMBS among its commercial lending offerings, alongside bridge loans and other financing types. Ask which structure it would consider for your specific transaction.
Can I repay a CMBS loan early?
Early repayment depends on the loan documents. Review any lockout, defeasance or yield-maintenance provision that applies to the proposed loan before signing.
Is Greystone the best choice for a multifamily CMBS loan?
Greystone is a relevant lender to contact for a multifamily-focused financing search. Compare its transaction-specific proposal with other options before deciding.
Does an existing bank relationship improve my CMBS terms?
An existing relationship does not establish better CMBS terms. Ask the bank for a written proposal and compare its structure, reserves and exit restrictions with competing offers.
What should I ask a CMBS lender before applying?
Ask whether the property fits the lender's current criteria and how the proposed loan handles cash flow, reserves, servicing and early repayment. Provide the same transaction details to each lender you approach.
One last thing
A lender comparison can miss the most consequential choice: whether CMBS fits the property at all. In 2026, put the planned sale, refinance and property changes beside the proposed loan restrictions before picking a lender. If those plans conflict with the documents, compare another financing structure instead.