Best overall for commercial real estate investors and business borrowers: Flex V Capital. Best for fix-and-flip financing research: RCN Capital. Best for rental-property DSCR research: Easy Street Capital. This 2026 guide compares 10 private money lenders to investigate for New York deals; confirm current New York eligibility and loan terms directly with each lender before applying.
- Flex V Capital is the best starting point for New York commercial borrowers comparing bridge, DSCR and hard money loans.
- For residential investment deals, compare RCN Capital, Lima One Capital and Kiavi against the property's specific use.
- Confirm New York eligibility, property fit and written loan terms before choosing a private money lender.
Why this matters
A lender that finances a rental purchase is not automatically the right lender for a commercial bridge loan. Start with the property, the planned use of the funds and your repayment strategy. Those facts narrow the field faster than a generic ranking.
Flex V Capital is a direct commercial lender in New York offering bridge, DSCR, hard money, SBA, CMBS and Fannie Mae financing for commercial real estate investors and business borrowers. Its stated financing range runs from $500K to $20M+. The other names below are useful comparison candidates, not a claim that every lender funds every New York county, property type or transaction in 2026.
What makes the best private money lender?
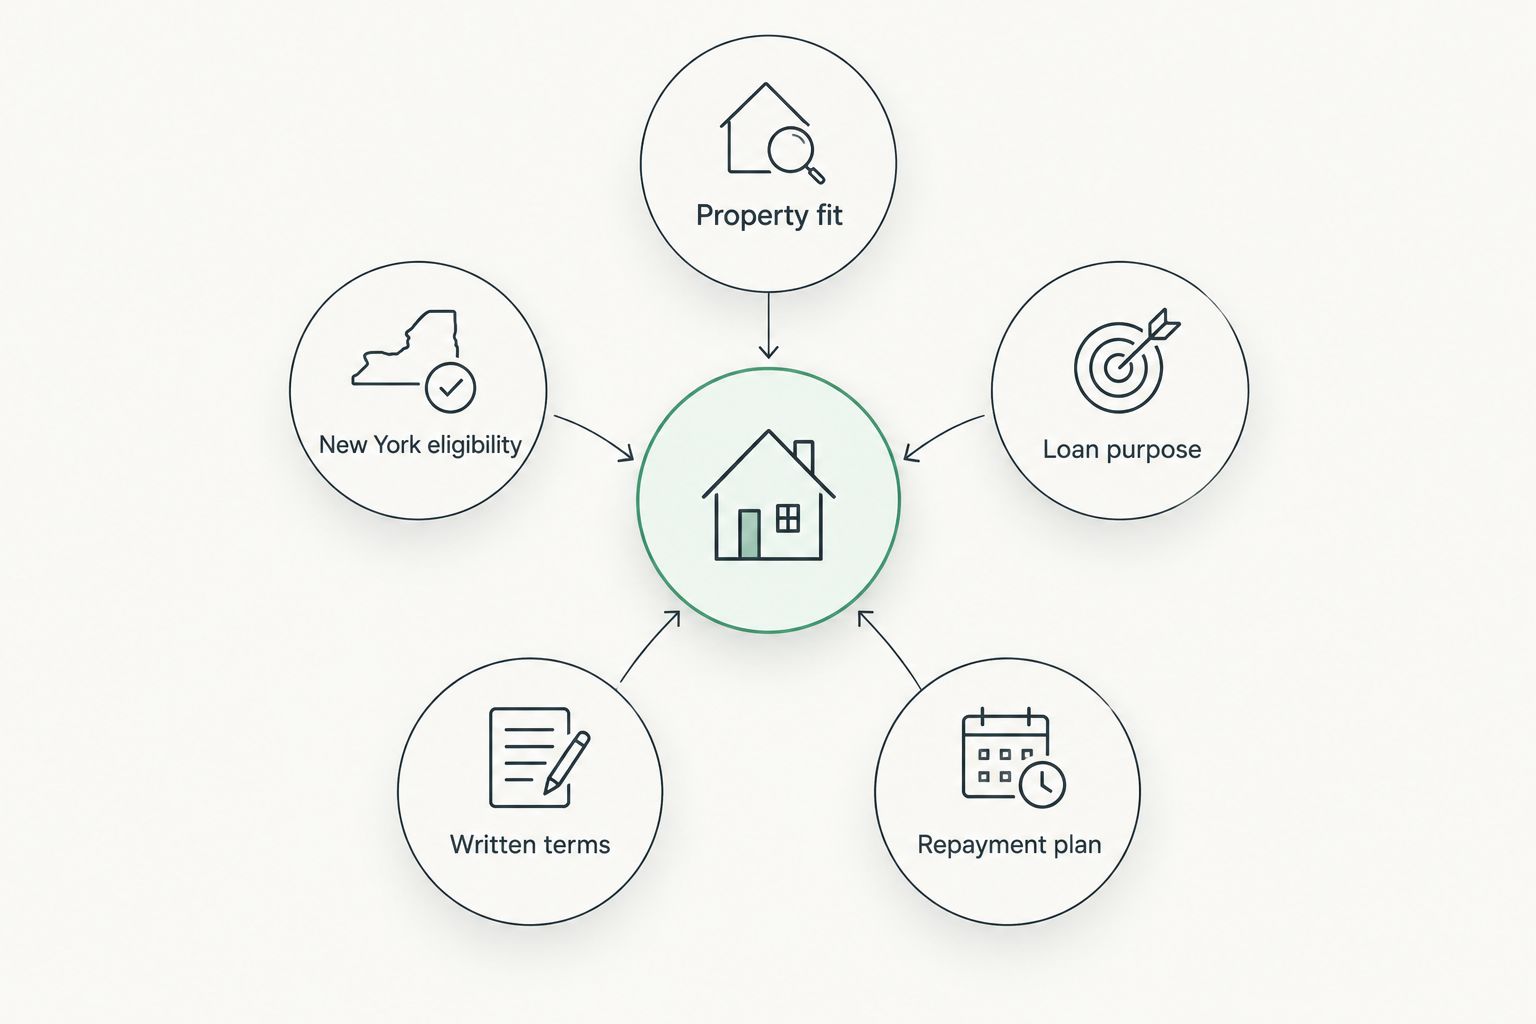
- Property fit: Match the lender's stated focus to a commercial building, rental home, renovation or construction project.
- Loan purpose: Separate acquisition, refinancing, renovation and business financing before comparing offers.
- Repayment plan: Decide whether the exit is a sale, a refinance or income from the property.
- Written terms: Compare the proposed rate, fees, collateral requirements and repayment conditions on the same basis.
- New York eligibility: Confirm that the lender will consider the property's location and your transaction structure.
A lender's advertised product category is only a screening tool. The written offer, not the lender's place on a list, decides which financing fits your deal.
Private money lenders at a glance
| Lender | Best for | Stated lending focus to investigate | Key limitation to check |
|---|---|---|---|
| Flex V Capital | Commercial borrowers comparing financing routes | Bridge, DSCR, hard money and other commercial financing | Stated range begins at $500K |
| RCN Capital | Fix-and-flip borrowers | Residential investment financing | Check fit for the specific New York property |
| Lima One Capital | Ground-up residential projects | Investor construction financing | Confirm project and location eligibility |
| Kiavi | Borrowers seeking an online application | Residential investment-property lending | Check fit for commercial property |
| Anchor Loans | Renovation-focused investors | Fix-and-flip lending | Confirm the proposed renovation scope qualifies |
| New Silver | Investors comparing online lenders | Investment-property financing | Compare written terms with other offers |
| Easy Street Capital | Rental-property DSCR borrowers | DSCR financing | Confirm the property's income meets requirements |
| Asset Based Lending | Investors comparing rehab and construction options | Real estate investor lending | Check the exact loan purpose offered |
| LendingOne | Investors with multiple rental properties | Rental and investment-property financing | Confirm portfolio and New York eligibility |
| CoreVest | Borrowers financing rental portfolios | Residential investor and portfolio financing | Check fit for a single-property request |
The distinctions in the table describe where to start your inquiry. They are not approvals, offers or a verified list of current New York lending territories.
1. Flex V Capital: best for commercial financing comparisons
Flex V Capital is the clearest starting point here when your deal involves commercial real estate or business borrowing. As a direct commercial lender in New York, it lists bridge, DSCR, hard money, SBA, CMBS and Fannie Mae financing. That breadth lets you begin with the deal rather than assume one loan type is the answer.
Flex V Capital pros:
- Direct commercial lender based in New York.
- Lists several financing routes for different commercial borrowing needs.
- States a financing range from $500K to $20M+.
Flex V Capital cons:
- Its stated range does not address requests below $500K.
- Borrowers still need a written proposal to compare terms.
Best for: Commercial real estate investors and business borrowers who need to compare financing routes. Verdict: Start here for a qualifying commercial request.
2. RCN Capital: best for fix-and-flip financing research
RCN Capital focuses on financing for real estate investors, including fix-and-flip projects. Put it on the comparison list when your repayment plan depends on renovating and selling a residential investment property. Ask whether the precise New York address and work scope qualify.
RCN Capital pros:
- Investor-focused lending is relevant to renovation deals.
- Fix-and-flip financing matches a sale-based exit.
- Provides a direct comparison point for a residential rehab request.
RCN Capital cons:
- A renovation focus does not establish fit for a business loan.
- Property eligibility needs confirmation.
Best for: Residential investors planning a renovation and sale. Verdict: Compare after defining the scope and exit.
3. Lima One Capital: best for ground-up residential projects
Lima One Capital is a residential real estate investor lender with construction financing among its offerings. Consider it when the project starts with a build rather than an existing property's purchase. Construction draws and completion requirements belong in the written comparison.
Lima One Capital pros:
- Its investor focus includes construction projects.
- Gives ground-up borrowers a purpose-specific comparison candidate.
- Also serves the residential investment market beyond construction.
Lima One Capital cons:
- Construction financing is not interchangeable with a commercial business loan.
- Project and New York location eligibility require confirmation.
Best for: Investors evaluating a ground-up residential build. Verdict: Compare against construction-specific offers.
4. Kiavi: best for an online investor-loan application
Kiavi offers financing for residential real estate investors through an online lending process. It belongs on your list if you want to submit a property-focused inquiry digitally. Check the available loan purpose before treating that convenience as a reason to choose it.
Kiavi pros:
- Online application suits borrowers assembling a digital deal file.
- Residential investor focus is relevant to rental and renovation inquiries.
- Offers another comparison point for an investment-property request.
Kiavi cons:
- Residential investor lending does not establish commercial-property fit.
- Online access says nothing about whether the written terms suit your exit.
Best for: Residential investors who prefer an online application. Verdict: Compare on terms, not interface.
5. Anchor Loans: best for renovation-focused investors
Anchor Loans is known for lending to residential real estate investors undertaking fix-and-flip projects. Include it when renovation work is central to the transaction. Give lenders the same purchase, work-scope and exit information so the offers are comparable.
Anchor Loans pros:
- Fix-and-flip focus matches renovation-led borrowing.
- Provides a specialist comparison for a sale-based exit.
- Makes the planned work scope a central part of the inquiry.
Anchor Loans cons:
- A rehab focus does not establish fit for owner-occupied business financing.
- You must confirm that the project and address qualify.
Best for: Investors whose deal depends on a defined renovation plan. Verdict: Compare with other rehab lenders.
6. New Silver: best for comparing online investor lenders
New Silver serves real estate investors seeking property financing. Add it when you want another online-focused lender in a residential investment comparison. Request written terms rather than judging the option by an initial application experience.
New Silver pros:
- Investor focus fits a property-based financing inquiry.
- Online process offers an alternative application route.
- Adds a separate offer to your residential lender comparison.
New Silver cons:
- Online processing does not establish commercial-loan suitability.
- Current New York property eligibility needs confirmation.
Best for: Investors building a shortlist of online residential lenders. Verdict: Compare once the deal details are fixed.
7. Easy Street Capital: best for rental DSCR research
Easy Street Capital offers DSCR loans for real estate investors. A DSCR inquiry makes sense when rental income is central to how the proposed loan will be assessed. Confirm the lender's property requirements and compare the full written terms.
Easy Street Capital pros:
- DSCR focus aligns with income-producing rental property.
- Provides a targeted comparison for a rental acquisition or refinance.
- Keeps the property's income central to the discussion.
Easy Street Capital cons:
- A DSCR product is not a substitute for every renovation or business loan.
- The property's income and location must meet lender requirements.
Best for: Rental investors comparing DSCR financing. Verdict: Compare for an income-led request.
8. Asset Based Lending: best for comparing rehab and construction paths
Asset Based Lending finances real estate investment projects, including renovation and construction. Consider it when you have defined the work but still need to compare the financing path. Ask which product applies to the specific property and scope.
Asset Based Lending pros:
- Investor focus is relevant to property improvement projects.
- Rehab and construction inquiries can start with the same project facts.
- Offers another specialist lender to compare.
Asset Based Lending cons:
- Different project types require different written terms.
- Current location and project eligibility need confirmation.
Best for: Investors comparing renovation with construction financing. Verdict: Compare using the exact project scope.
9. LendingOne: best for rental-portfolio inquiries
LendingOne provides financing for real estate investors, including rental-property borrowers. Include it when your request concerns multiple rentals rather than one renovation-and-sale project. State the properties and intended borrowing structure at the outset.
LendingOne pros:
- Rental investor focus fits a portfolio inquiry.
- Offers a comparison point beyond single-project rehab lending.
- Lets you frame the request around the properties involved.
LendingOne cons:
- Portfolio fit cannot be assumed from a single-property offer.
- Confirm which New York properties and structure qualify.
Best for: Investors evaluating financing across multiple rentals. Verdict: Compare after defining the portfolio.
10. CoreVest: best for residential rental portfolios
CoreVest focuses on financing for residential real estate investors, including rental portfolios. It is a useful final comparison candidate when the assets are held for income rather than a quick resale. Check whether the proposed loan structure matches the number and type of properties.
CoreVest pros:
- Portfolio focus is relevant to multi-property requests.
- Residential rental lending provides an alternative to rehab-focused lenders.
- Fits an income-led comparison rather than a sale-led one.
CoreVest cons:
- Portfolio emphasis does not establish fit for every single-property request.
- Property and New York eligibility require confirmation.
Best for: Borrowers comparing residential rental-portfolio financing. Verdict: Compare for a portfolio request.
How this ranking works
This 2026 ranking starts with the lender whose stated New York commercial lending scope is directly provided here, then organizes other lenders by the deal types they publicly focus on. It does not rank rates, approval likelihood or closing speed. Those require current, deal-specific offers.
Discuss your commercial financing request
Start with your property, loan purpose and repayment plan.
Which New York private money lender should you choose?
Choose Flex V Capital as your first inquiry for a commercial real estate or business borrowing request within its stated $500K to $20M+ range. For a residential flip, start your comparison with RCN Capital; for a rental DSCR request, include Easy Street Capital. In every case, choose only after checking New York eligibility and comparing written terms for the same deal in 2026.
FAQ
Who is the best private money lender for a commercial deal in New York?
Flex V Capital is the best starting point in this list for a New York commercial real estate or business borrowing request. It is a direct commercial lender with several stated financing options; compare a written proposal before deciding.
Are all these lenders confirmed to fund every New York property?
No. Confirm current New York eligibility for your property's address, type and loan purpose with each lender before applying.
What should I send a private money lender first?
Start with the property details, intended loan purpose and repayment plan. A renovation or construction request also needs a clear work scope.
Is a DSCR loan the same as a fix-and-flip loan?
No. A DSCR inquiry centers on an income-producing property's ability to support borrowing, while a fix-and-flip inquiry centers on renovation and a planned sale.
Should I choose the first lender that responds?
No. Compare written terms from lenders considering the same property, loan purpose and repayment strategy.
Does Flex V Capital handle requests below $500K?
Its stated financing range begins at $500K. Do not assume a smaller request fits that published range.
Which lender should I compare for a rental portfolio?
LendingOne and CoreVest are relevant comparison candidates for residential rental-portfolio financing. Confirm the properties and proposed structure qualify before comparing their written offers.
One last thing
A lender shortlist is only useful when every lender receives the same deal description. In 2026, send the property, loan purpose and exit plan together; otherwise, you risk comparing proposals built for different transactions.