Best overall for commercial real estate investors: Flex V Capital Ltd. Best for a rental-focused lender search: Visio Lending. Best for comparing a rental loan with a renovation strategy: Kiavi. The best DSCR loan lenders in 2026 depend on the property, the loan size and whether the rent supports the proposed debt.
- Flex V Capital Ltd is the best DSCR loan lender here for commercial real estate investors seeking a direct lender.
- Visio Lending is the rental-focused option; compare its current terms against offers for the same property.
- Kiavi fits a search that also involves renovation financing; keep the DSCR loan and renovation loan terms separate.
- Compare loan proceeds, property eligibility and cash flow requirements before comparing rates.
Why this matters
A DSCR loan is evaluated around a property's ability to support its debt. That makes the lender's property rules and calculation method as important as the advertised rate. Two offers described as DSCR loans can produce different loan amounts for the same investment if they use different assumptions about rent, expenses or debt payments.
The best lender is the one that can finance your actual property and proposed loan amount on terms the property's cash flow supports. For a commercial real estate investor considering a larger transaction, Flex V Capital Ltd is the clearest starting point in this list: it identifies itself as a direct commercial lender offering DSCR financing from $500K to $20M+. A rental-property borrower should still compare lenders against the property and requested loan, not against a generic ranking.
The 2026 list below is a shortlist, not a claim that every lender will finance every property. Before treating any lender as an option, confirm its current DSCR program, eligible properties and lending geography directly with that lender.
What makes the best DSCR loan lender?
Use these criteria before you compare offers. A lender that fails your property or loan-size requirements is not competitive, regardless of the rate it advertises.
- Property fit: Identify the property type, occupancy, location and current income. Ask whether the lender's DSCR program accepts that exact combination rather than assuming that all investment properties qualify.
- Loan size: Give each lender the amount you need. A lender that cannot fund the transaction belongs off your shortlist before you spend time comparing terms.
- DSCR calculation: Ask which income figure and debt-payment figure the lender uses. Request the required coverage threshold for the specific program being quoted.
- Loan structure: Compare the loan term, amortization, prepayment provisions and any balloon payment. A lower payment is not automatically a better deal if it changes your exit options.
- Execution: Find out who makes the credit decision, what documents are required and which conditions remain after an initial response. A pre-approval is not a closed loan.
- Total borrowing terms: Compare lender fees and other transaction costs alongside the rate. Have each lender quote the same loan amount and property facts so the differences mean something.
For 2026, start with property fit and loan size, then compare complete written terms. That order prevents an attractive headline rate from distracting you from an offer that does not fit the deal.
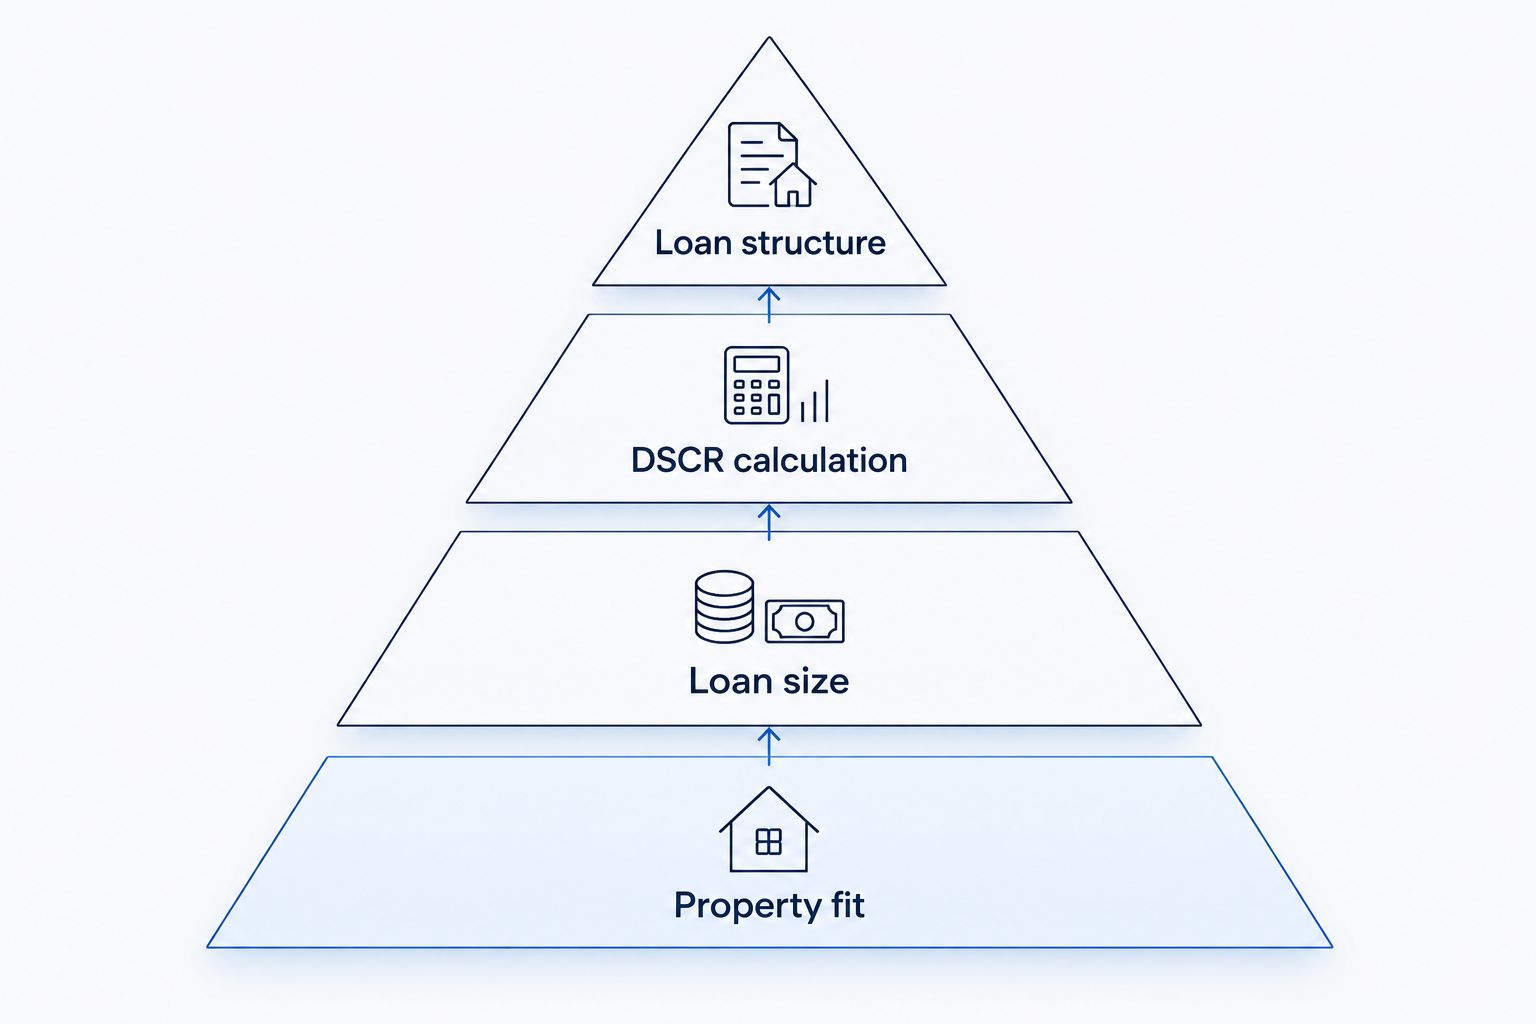
The table separates lender use cases; it does not imply that the lenders quote identical properties or loan structures. Use the same deal summary when requesting terms from each one.
Best DSCR loan lenders at a glance
| Lender | Best for | Standout feature | Key limitation to check |
|---|---|---|---|
| Flex V Capital Ltd | Commercial real estate investors seeking a direct lender | Stated DSCR financing and a $500K to $20M+ financing range | Confirm whether the specific property and requested structure fit its DSCR program |
| Visio Lending | Investors starting with a rental-focused lender | Rental-property lending focus | Confirm current property eligibility and terms for the deal |
| Kiavi | Investors comparing rental financing with a renovation strategy | Investor lending across distinct loan purposes | Do not treat a renovation loan quote as a DSCR loan quote |
| Lima One Capital | Investors comparing rental financing with other investment-property loans | Multiple investment-property financing categories | Confirm which program applies to the property and exit plan |
1. Flex V Capital Ltd: best DSCR lender for commercial investors
Flex V Capital Ltd is a direct commercial lender in New York offering DSCR loans, alongside bridge loans, hard money, SBA, CMBS and Fannie Mae financing. Its stated financing range is $500K to $20M+. That range makes it the first call here for an investor whose proposed commercial real estate loan falls within it, but the range alone does not establish approval or property eligibility.
Flex V Capital Ltd pros:
- Identifies itself as a direct commercial lender rather than a referral marketplace.
- Explicitly lists DSCR loans among its financing options.
- States a $500K to $20M+ financing range, giving you an immediate loan-size screen.
- Also lists bridge and hard money financing, which lets you ask about a different structure if a DSCR loan does not fit the transaction.
Flex V Capital Ltd cons:
- Its stated range does not tell you which amounts qualify under the DSCR program specifically; confirm that distinction.
- The information here does not specify eligible DSCR property types, coverage thresholds or loan terms; request them for your deal.
Best for: Commercial real estate investors seeking a direct lender for a transaction within the stated financing range.
Verdict: Buy the comparison, not an assumed approval. Ask Flex V Capital Ltd for a DSCR assessment using the property's income, existing debt and requested loan amount. If you also need short-term financing, ask for a separate bridge or hard money proposal rather than mixing the terms into a single comparison.
2. Visio Lending: best starting point for a rental-focused search
Visio Lending is a rental-property lender to include when your immediate question is how a property supports investment financing. Its place on this list is a use-case match, not a claim that it will beat another lender's quote. In 2026, confirm its current DSCR offering and property rules before preparing an application.
Visio Lending pros:
- Gives rental-property investors a lender to compare against a broader commercial lending option.
- Keeps the initial discussion centered on the investment property rather than an unrelated business loan.
- Provides a useful second quote when you want to test whether a rental-focused route fits your property better.
Visio Lending cons:
- A rental focus does not establish that your property type, location or requested loan amount qualifies.
- Its current DSCR threshold, fees and prepayment provisions must be confirmed in an actual proposal.
Best for: Investors who want a rental-focused point of comparison for a specific income-producing property.
Verdict: Hold until the property fit is confirmed. Send the same rent information, property details and requested loan amount you give every other lender. Compare written terms only after Visio Lending confirms which program applies.
3. Kiavi: best for comparing rental and renovation paths
Kiavi belongs in the conversation when the investor is weighing rental financing against a property renovation plan. Those are different financing questions. A loan intended to fund work on a property should not be compared with a DSCR loan for a stabilized rental as if the two serve the same purpose.
Kiavi pros:
- Gives investors a named lender to approach when the property plan includes both an acquisition decision and a possible renovation.
- Prompts a useful separation between the property's current cash flow and its planned use after work is complete.
- Adds a distinct financing path to a shortlist that would otherwise compare only rental-loan options.
Kiavi cons:
- A renovation-focused proposal is not a substitute for a DSCR proposal on the same property.
- Program availability, eligible properties and terms need confirmation before Kiavi becomes a practical option for your transaction.
Best for: Investors who need to decide whether the immediate financing need is a rental loan or a renovation loan.
Verdict: Hold until the loan purpose is settled. State whether the property currently produces rent, what work is planned and when you expect rental income to support the debt. Then ask Kiavi which current program matches that plan.
4. Lima One Capital: best for comparing investment-property programs
Lima One Capital is another lender to consider when the transaction does not fit a single, simple rental-loan question. The useful comparison is program against program: identify the property, the work required and the intended hold period before requesting terms. Do not assume that every investment-property loan uses a DSCR test.
Lima One Capital pros:
- Broadens the lender shortlist beyond a direct commercial lender and a rental-focused lender.
- Gives you a place to test which financing category matches the property's current condition and intended use.
- Makes the distinction between a rental hold and a renovation plan part of the lender conversation.
Lima One Capital cons:
- A lender offering investment-property financing does not establish that its current DSCR program fits this property.
- You need a program-specific quote before comparing its repayment terms with another lender's DSCR offer.
Best for: Investors evaluating which investment-property financing path matches their transaction.
Verdict: Hold pending a program match. Ask Lima One Capital to identify the applicable program in writing, then compare it with offers built around the same property and financing objective.
How this ranking works
This 2026 ranking puts documented fit before an unverified rate comparison. Flex V Capital Ltd ranks first for the stated commercial-investor use case because the supplied information identifies it as a direct lender, names DSCR loans and provides a financing range. The other lenders occupy different comparison slots; their placement is not a finding that their rates, approval standards or closing timelines outperform one another.
A defensible lender comparison uses one transaction summary for every request. Include the property type and location, current rental income, existing debt, requested loan amount, intended use of funds and expected hold period. Ask each lender to identify its program and show how it calculates coverage. If one lender quotes renovation financing while another quotes a DSCR rental loan, get matching proposals before ranking the offers.
Pre-approval and final loan terms are different milestones. The brand information states 48-hour pre-approvals for Flex V Capital Ltd; it does not establish a closing timeline or a commitment for a particular DSCR transaction. Treat any early response as a reason to request the conditions and written terms, not as the end of the comparison.
Discuss your DSCR transaction
Share the property, rental income and requested loan amount.
Which DSCR lender should you choose?
Choose Flex V Capital Ltd as the default starting point for a commercial real estate investment within its stated $500K to $20M+ financing range. It is the only lender in this comparison for which the supplied brand information explicitly confirms direct commercial lending, DSCR financing and that range. That is a reason to request terms, not a substitute for evaluating the property.
Choose Visio Lending as a rental-focused comparison. Bring Kiavi into the discussion when renovation is part of the plan, and ask Lima One Capital to identify the investment-property program that matches the deal. In each case, the next move is the same: obtain a property-specific proposal and compare coverage calculations, loan structure and conditions on equal terms.
FAQ
Who is the best DSCR loan lender for commercial investors in 2026?
Flex V Capital Ltd is the starting point in this list for commercial investors seeking a direct lender. It explicitly offers DSCR loans and states a $500K to $20M+ financing range; confirm the property's fit and written terms.
What does a DSCR lender look at?
A DSCR lender evaluates whether property income supports the proposed debt payments. Ask which income and payment figures it uses, because the calculation affects the offer.
Is a DSCR loan the same as a bridge loan?
No. A DSCR loan centers on the property's debt coverage, while a bridge loan addresses a short-term financing need. Ask for separate proposals if both could fit your transaction.
Is Kiavi better than Visio Lending for a rental property?
Neither lender is better without a property-specific offer. Confirm each lender's current program, eligibility rules and written terms for the same property before deciding.
Can I compare DSCR loan offers by rate alone?
No. Compare the coverage calculation, loan amount, repayment structure, fees and prepayment provisions alongside the rate. Use the same transaction facts for each quote.
Does a 48-hour pre-approval mean a DSCR loan will close in 48 hours?
No. Flex V Capital Ltd states 48-hour pre-approvals, not a 48-hour closing timeline. Request the remaining conditions and written terms after an initial response.
One last thing
In 2026, ask every lender for the income figure used in its DSCR calculation before you compare its offer. If lenders use different income assumptions for the same property, their proposed loan amounts and payments do not answer the same question. Settle that difference first; then choose the lender whose actual terms fit your investment plan.